Estero Bay Strategic Management
Open navigation Menu
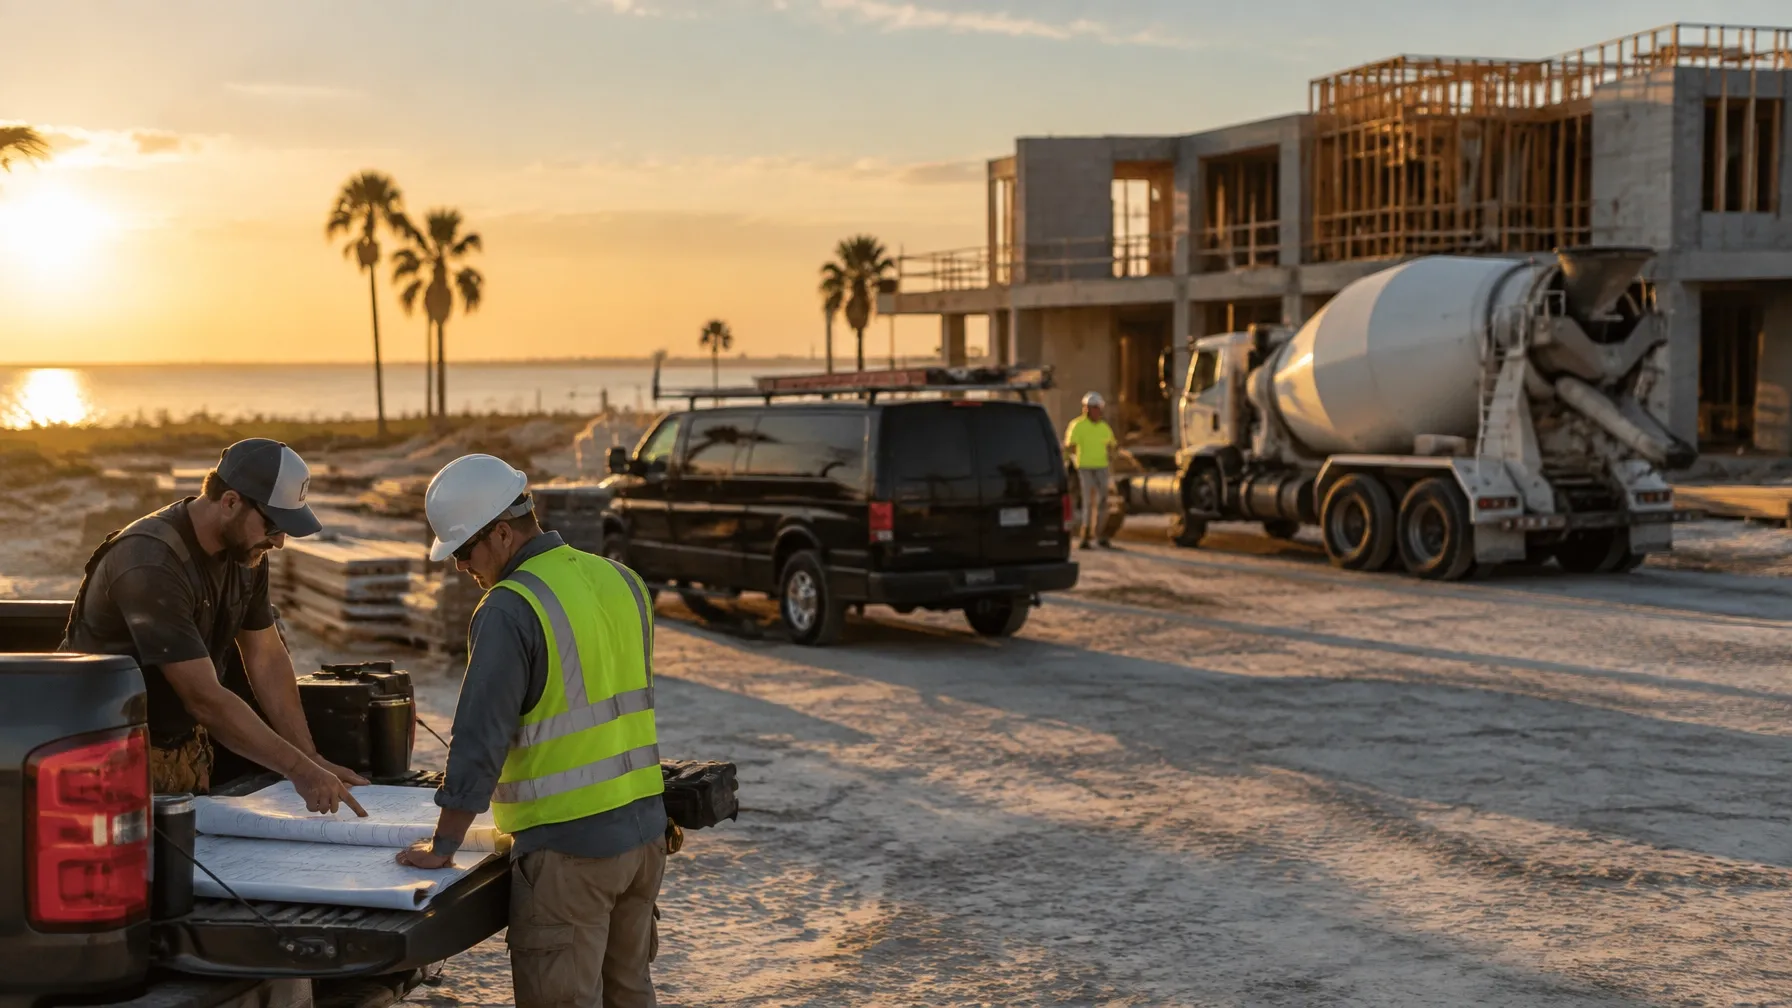
Commercial trades crew with a ready-mix truck and service van at a Southwest Florida job site

Southwest Florida operating advisory

We run the back office so you canborrow against real numbers.

Estero Bay takes over AP/AR workflows, job costing, Work-in-Progress tracking, and invoicing so billing happens the moment a job completes — audit-ready financial closes by the 10th business day, plus a rolling 13-week cash forecast and bank-ready credit files.

$500K–$25M

Annual revenue clients

13-week

Rolling cash model

Day 10

Audit-ready close

Our core services

What we solve day to day

Most operators do not need theoretical consulting. They need a disciplined operating rhythm that turns field work into cash and produces bankable records.

01

Back-Office Management & Accrual Accounting

Invoicing, AP/AR workflows, job costing, and WIP tracking that turn completed work into collected cash.

Explore the service
02

13-Week Cash Flow Forecasting

A rolling weekly schedule for collections, vendor payments, payroll, tax reserves, and the decisions between them.

Explore the service
03

Commercial Loan & Bank Line Packaging

Credit files, add-back recasting, collateral reporting, and DSCR discipline built for real lender conversations.

Explore the service

Illustrative financial scenario

Working capital should be visible before it becomes a problem.

When receivables sit uncollected past 60 or 70 days, operational liquidity is trapped on the balance sheet. This is the kind of picture we build, update, and use with owners and lenders.

Illustrative financial scenario

Working capital model

Baseline → weekly management

Annual gross revenue

$5,000,000

Current DSO

70 days

Target baseline DSO is modeled at 42 days through immediate billing and structured payment terms.

Interest savings assume an illustrative 9.50% commercial bank rate on working capital.

Actual liquidity release depends on contract terms, customer credit, and project milestones.

Trapped receivables

$972,222

Cash uncollected at current DSO

Modeled release

$388,889

Capital freed if compressed to 42 days

Est. LOC interest saved

$36,944 / yr

At a 9.5% illustrative rate

DSCR discipline

1.48x

Illustrative normalized outcome; target above 1.30x

Illustrative only. Not a guarantee of savings or credit approval.See the full model

Representative client engagements

How back-office discipline unlocks capital

Anonymized examples demonstrate the measurable result of restructuring back-office operations and preparing institutional loan packages.

Specialty commercial subcontractor$4.8M revenue

Overcoming a $750K bank credit line deadlock

Problem

Invoicing lagged 25 days; receivables stretched to 72 days and crossed the bank’s 90-day collateral threshold.

Intervention

Rebuilt field sign-offs, started immediate billing, automated payment cadences, and recast two years of owner add-backs.

Result in 90 days

DSO dropped to 42 days, releasing over $380,000 and restoring the $750,000 revolving line.
Heavy materials & hauling operator$12.5M revenue

Fleet refinancing & debt covenant shielding

Problem

Tax depreciation created paper losses and a reported DSCR of 0.98x against a 1.25x requirement.

Intervention

Installed accrual WIP reporting, audited $420,000 in non-recurring expenses, and presented the credit package directly to the lender.

Result in 90 days

Normalized DSCR reached 1.48x and secured a $1.4M equipment term loan without equity dilution.

Paul Francis Schmieder, Managing Principal

Managing principal

Paul Francis Schmieder

Background & pedigree

Direct operating & turnaround experience

Traditional bookkeepers record past data. Statutory CPAs prepare annual tax returns designed to minimize taxable income. But when an operating company needs a $1M to $5M commercial credit line, standard tax returns and messy desktop records can disqualify it in bank underwriting.

Paul Francis Schmieder brings more than two decades of hands-on executive turnaround leadership, industrial manufacturing management, and capital-intensive operating experience. He has worked directly with commercial banking relationships, equipment finance divisions, corporate attorneys, and bank loan committees.

Estero Bay does not hand you an academic report. It steps into the office and establishes the operating systems required to sustain growth, defend DSCR, and secure capital.

Operating focus

Field-to-ledger execution

Bank fluency

Direct credit defense

SW Florida local

On-site presence

Read the full background

Frequently asked questions

Direct answers for business owners

How does your service differ from an outside tax CPA?

Your CPA focuses backward on tax compliance and legally minimizing income taxes. We focus forward on operational health: daily AP/AR workflows, job-cost accruals, weekly 13-week cash management, and credit packages that make your business bankable. We coordinate directly with your CPA so year-end tax strategies don't accidentally breach bank debt covenants.

How does this differ from hiring a local bookkeeper?

Bookkeepers typically perform basic cash-basis data entry and bank reconciliations after the month has closed. We install operating procedures that connect field work directly to invoicing, manage rolling liquidity forecasts, calculate monthly Debt Service Coverage Ratios (DSCR), and interface with commercial bank loan officers.

What happens during the first 30 days (Foundation Diagnostic)?

We conduct a forensic review of your General Ledger, clean up balance-sheet misclassifications, identify and document all legitimate owner add-backs, calculate your baseline DSCR across trailing twelve months, and build your company’s first rolling 13-week cash-flow forecast.

What documentation do you need to begin?

Prior two years of corporate tax returns, trailing twelve-month profit and loss statements, current balance sheet, detailed accounts receivable and accounts payable aging summaries, and copies of existing commercial loan or equipment credit agreements.

How does the initial onboarding fee relate to monthly retainers?

The Foundation Diagnostic ($5,000–$15,000) is a mandatory, one-time 30-day sprint required to audit and normalize your records. Once clean books and cash rhythms are established, clients transition seamlessly into predictable monthly recurring retainers.

Clear retainer structure

Engagement architecture

Predictable fees based on revenue scale and operational complexity. Every engagement begins with a Foundation Diagnostic.

Mandatory 30-day sprint

Foundation Diagnostic

$5,000–$15,000

One-time onboarding fee

  • Forensic general ledger audit
  • Owner add-back recasting
  • Baseline DSCR calculation
  • Initial 13-week cash model setup
Schedule audit
Emerging · $500K–$1.5M

Tier 1 Retainer

$2,500–$3,500/mo

Monthly recurring retainer

  • Back-office takeover & cleanup
  • Automated AP/AR processing
  • Day-10 monthly accrual close
  • Weekly 13-week cash forecasting
Select Tier 1
Growth · $1.5M–$5M

Tier 2 Retainer

$4,500–$6,500/mo

Complete controller pod

  • Full back-office management
  • Work-in-Progress (WIP) tracking
  • Active bank credit line oversight
  • Quarterly DSCR covenant audits
Select Tier 2
Mid-market · $5M–$15M

Tier 3 Retainer

$7,500–$12,500/mo

Multi-entity & CapEx

  • Multi-entity ledger consolidation
  • Heavy equipment CapEx packaging
  • Institutional credit files for lenders
  • External CPA & insurance coordination
Select Tier 3

Confidential review

Let’s review your back-office & banking needs.

Connect directly with Paul Francis Schmieder to review your invoicing lag, 13-week liquidity forecast, or upcoming bank loan requirements.

Phone239-940-6869

Emailinfo@estero-bay.com

Office23150 Fashion Drive, Suite 232
Estero, FL 33928